
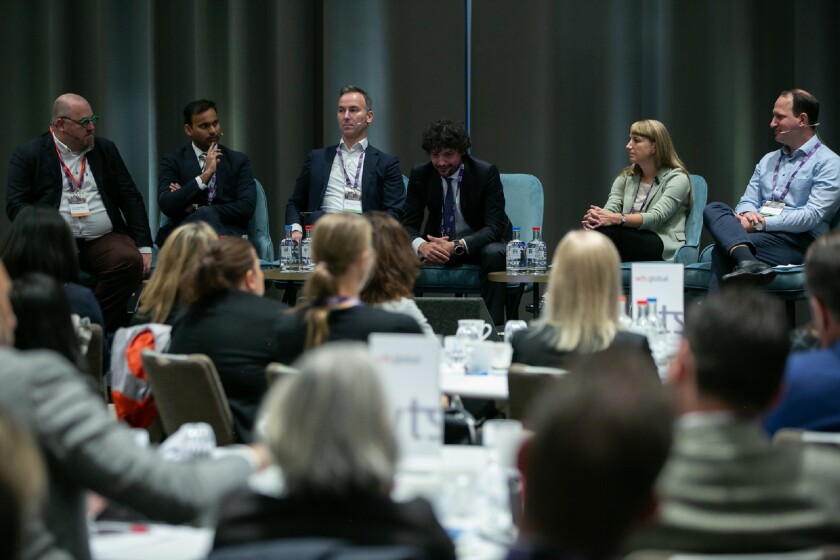
The OECD’s pillar one-related transfer pricing rules remain too complex and the scope should be expanded, according to speakers at ITR’s Global TP Forum Europe, held in Amsterdam yesterday, September 28.
“We think it’s really important to have a simplification of the TP rules,” said Mauro Faggion, TP expert at the European Commission.
Faggion stressed that the need for simplification provided a “clear mandate” and that there is a “real demand” from businesses.
Other panellists including Vikram Chand, professor of law at the University of Lausanne in Switzerland, agreed with Faggion’s comments.
“A lot of people will agree that these rules are not simple to understand at this stage. The way the proposal has been set right now in the progress report looks complex,” he explained.
Failure to address the complexity of the rules could jeopardise the success of the OECD’s project, particularly if multinationals continue to show strong reluctance.
Jens Krüger, senior manager of TP at pharmaceutical company Boehringer Ingelheim in Germany, explained why the rules needed to be simplified.
“We need to have the data from our systems – to find where they are and compute Amount A and B. What we did is a list of pillar one and two and all the different definitions.
“Then we also did a list where we compared the definition of pillar two, which we might be able to use for pillar one,” said Krüger.
“Simplification for us would mean shortening this list. That would be my pledge for simplicity,” he added.
Size matters
However, the simplification of pillar one rules is not the only amendment that tax directors expect. Some also demand a wider scope that captures more corporations.
Under the current proposals, pillar one targets the large and most profitable companies. Those subject to the rule must have total revenues that exceed €20 billion ($19.2 billion) and their profitability measured against the total revenues must exceed 10%.
“Neutrality is also about ensuring that the system applies as broadly as possible,” said Chand. “From that point of view, you may say that a lot of multinational enterprises are not caught by these rules.”
But other corporations fear digital taxes already target companies that are not fully technology driven and that increasing the scope could also create more risk of double taxation.
Marta Pankiv, senior director and head of group tax at software company Tricentis in Vienna, said digital services tax (DST) remained “quite an issue”.
“Every time we are trying to figure out whether we can sell in a location, the first thing that pops up would be DST and VAT. When we talk about pillar one allocation – how about other businesses? DST is very broad,” she said.
“There are companies that are not necessarily all technology but are selling technology goods – the scope is very broad. It’s also double taxation for us,” added Pankiv.
In 2021, countries including France, the UK, Austria, Italy, Spain, and the US reached an agreement to implement the DST during the interim period of pillar one’s implementation.
These jurisdictions plan to offer tax credits once pillar one is adopted – an initiative that Pankiv has welcomed, but the limited number of countries continues to pose a risk for businesses.
“My hope is that countries are willing to be aware that it’s not about imposing tax and getting quick money. I hope there will be some compromise on the road,” she said.








